How 'liar loans' undermine sound lending practices
- Written by: Maria Yanotti, Lecturer of Economics and Finance Tasmanian School of Business & Economics, University of Tasmania
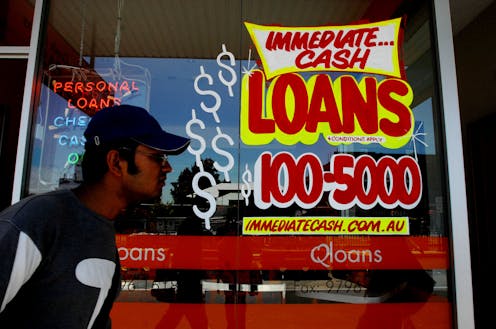
How truthful are we when it comes to negotiating loans in Australia?
With increasing pressure on the housing market, some of us might be tempted to stretch the truth to secure a mortgage on our dream property - but research shows that this practice can have serious repercussions.
Recent news reports have alerted borrowers to the dangers of “liar loans”, based on the findings of a new UBS research study. A liar loan is a no-documentation loan that is approved on the basis of unverified and possibly false information about income, assets or capacity to repay.
In the United States, where many loan applications have been approved without any information on the borrower’s income and assets - these liar loans have been implicated as one of the reasons for the global financial crisis.
Read more: Financial literacy is a public policy problem
Should we be worried in Australia?
The UBS study found that a third of Australian mortgage borrowers reported being “not factual or accurate” in their mortgage applications. Being “not accurate” is not the same thing as being a “liar”. However, we need to be aware and pro-active to avoid poor standards and practices.
They further estimate that there is roughly US$500 billion (A$657.95 billion) worth of factually inaccurate mortgages on banks’ books in Australia. This is worrying, because it could mean that borrowers are taking on bigger debts than they can actually afford, falling into financial stress or even losing their homes.
The Australian situation
In Australia, when borrowers apply for a mortgage they need to provide documentation that verifies their employment history, creditworthiness, and overall financial situation. Borrowers are required to provide a payslip or most recent tax returns, and show that they have been employed in the same job for at least 12 months.
Other documentation may include: credit card and bank statements; sales contract; confirmation of rental income if purchasing an investment property; and more. The mortgage originator may perform credit checks and bankruptcy or default searches.
Some mortgage borrowers may not be required to provide much documentation if they are existing clients of the bank and already have a strong credit history.
In my research I found that 88.8% of mortgage applicants were existing customers of the bank where they apply for a mortgage, and had been so for 9.3 years on average. But low documentation loans exist for self-employed borrowers.
Where accuracy of mortgage applications becomes difficult to determine is when estimating the expenses of the household. Mortgage applicants are asked about their monthly expenses to assess whether they can service the debt without major stress. Here, applicants may be “mostly factual and accurate” or even “partially accurate” when trying to calculate their monthly expenses. After all, how many people actually keep accurate and up-to-date spreadsheets of all their expenses?
Debts outstanding with other financial institutions or family and friends may also be misreported. In addition, mortgage lenders who receive commissions linked to loan size have incentives to overestimate borrower’s incomes and underestimate expenses.
Australian version of liar loans?
These arguments do not suggest that there is no “lying” or “truth hiding” in mortgage applications in Australia, but that it may not be comparable to the trend of “liar loans” seen in the US.
More importantly, banks do not rely only on their clients’ word. Banks estimate monthly expenses and uncommitted income for their clients based on borrower characteristics and solid financial records.
Data from previous research reveals that banks estimate on average A$1,637 more on monthly expenses than applicants report. Based on the bank’s calculations, housing investors underestimate their monthly expenses by A$1,932 on average, while owner-occupiers underestimate by A$1,560 on average.
Similarly, mortgage applicants report their monthly uncommitted income to be on average A$702.5 more than what the bank estimates it to be. Housing investors only overestimate their monthly uncommitted income by A$174 on average, while owner-occupiers overestimate by A$840 on average.
Due diligence required from both banks and borrowers
Research finds that mortgage features (for example fixed or adjustable rates, maturity, loan-to-value ratio, and so on) help borrowers select mortgage products that are affordable and safer for them, with the guidance of mortgage lenders and brokers.
The research further finds that lenders should make sure that borrowers have the financial capacity to repay their loans out of income or by selling assets under plausible conditions, and not by relying on the value of the collateral.
Mortgage delinquency and default may rise due to excessive risk taking in mortgage lending combined with deteriorating economic conditions; or due to falling income and rising unemployment during a housing downturn. This later case is more likely the potential threat in the Australian current environment.
Read more: Financial crises 101 could provide lessons for all
The Australian Prudential Regulatory Authority (APRA) and the Reserve Bank of Australia (RBA) perform stress tests to check the financial system’s resilience. Along with APRA’s macro- and micro-prudential regulations, some lenders are introducing higher requirements and credit restrictions on potential borrowers.
These include obtaining more information on the clients, which helps assess credit and default risks and helps design and target financial products to specific type of borrowers. There is however risk of mortgage discrimination.
More careful monitoring needed
Mortgage risks often relate to mismatches between the products used by households and their financial capabilities and ability to bear risks. For that reason, mortgage product characteristics should be monitored carefully both by banks and borrowers.
The Organisation for Economic Co-operation and Development (OECD) suggests that financial authorities should make sure lending standards are sound, both in the banking and non-banking sectors. It is important that banks do not face incentives encouraging excessive risk taking.
Requiring more transparency, reinforcing consumer protection and financial education encourages sound lending and borrowing practices.
Authors: Maria Yanotti, Lecturer of Economics and Finance Tasmanian School of Business & Economics, University of Tasmania
Read more http://theconversation.com/how-liar-loans-undermine-sound-lending-practices-87073


 Daily Bulletin


